


English README | 简体中文 README | 繁体中文 README
AlphaPurify: Factor research for quants
AlphaPurify Python library for factor construction, preprocessing, backtesting, and factor return attributions to help quants rapidly validate ideas.
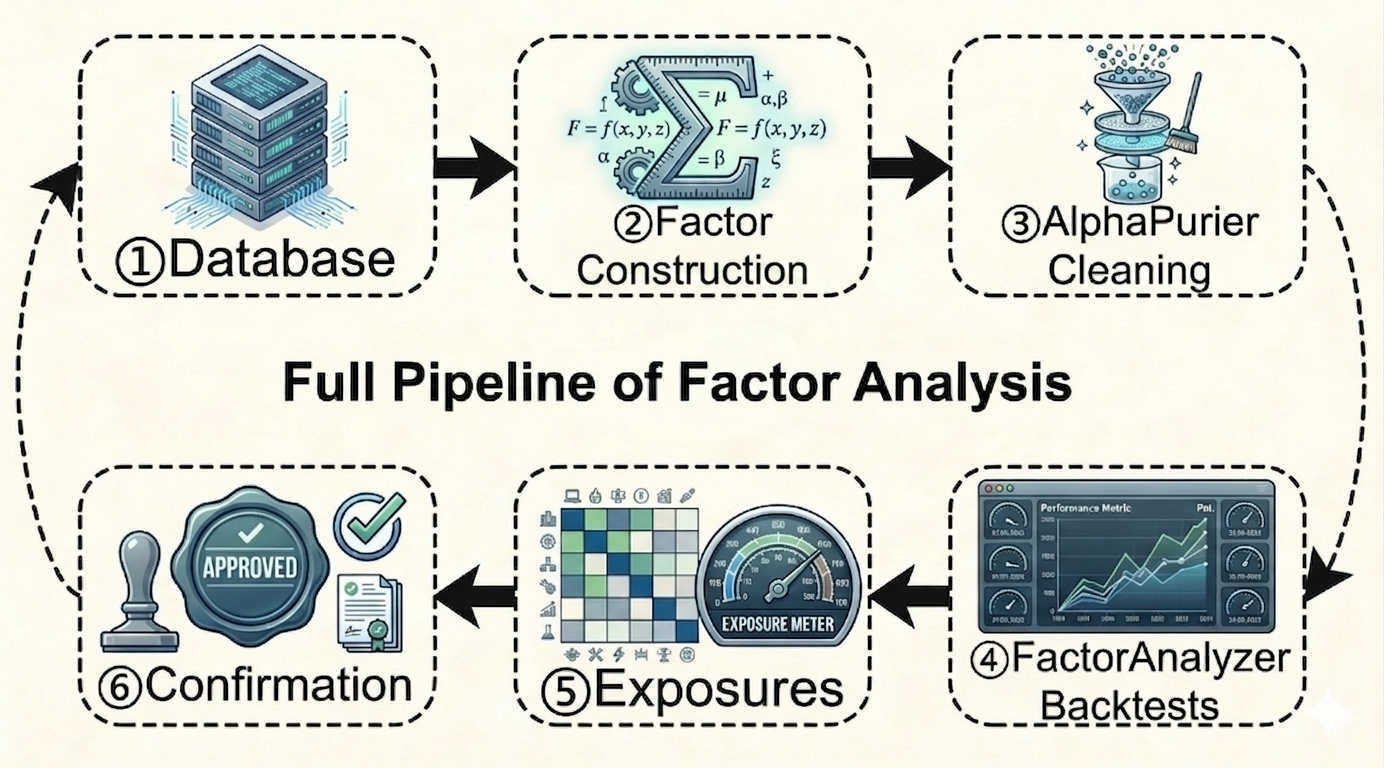
4 Main Modules:
1.alphapurify.FactorAnalyzer — for IC/ Rank IC testing and Long/ Short/ Long-Short quantile backtests.
2.alphapurify.AlphaPurifier — for factor preprocessing, including 40+ Winsorization, Neutralization, and Standardization methods (e.g., ridge regression, lasso regression, PCA decomposition, etc.).
3.alphapurify.Database — for financial data aggregation, factor construction, and factor storage.
4.alphapurify.Exposures — for factor correlation analysis and factor-based return attribution.
Pipeline Overview
Full Documents & Examples: English Docs
Key Features:
- Extremely Fast — Processes 4 Millions+ rows (15 years CSI 300) including long/short, long-short, IC backtests and creates 4 interactive reports in under 25 seconds (on a standard i7 CPU).
- 40+ Preprocessing Methods — Built-in professional factor cleaning tools supporting workflows from ultra high-frequency to low-frequency data.
- 1:1 Production-Grade Backtesting — Fully vectorized modeling of transaction fees, slippage, rebalancing, and dynamic weight drift to ensure reliable and rigorous backtest results.
- White-Box Backtesting — Empowering you to visually track weight transitions and asset returns at ANY timestamp, for ANY position direction, and within ANY quantile bin.
AlphaPurify vs Other Quant Libraries
| Feature / Library | AlphaPurify | Qlib | Backtrader | Alphalens | QuantStats | Pyfolio |
|---|---|---|---|---|---|---|
| Computation Speed | 🚀 Extremely Fast (Rust vectorized + multiprocessing) | ❌ Slow (heavy infrastructure) | ⚠️ Medium | ✅ Fast | no backtest | no backtest |
| Factor Preprocessing (40+) | ✅ Built-in | ⚠️ Limited | ❌ No | ❌ No | ❌ No | ❌ No |
| OOM Protection | 🟢 High (Zero Copy) | ❌ Low (Heavy DataFrame Cache) | 🟢 High | 🟢 High | no backtest | no backtest |
| Cross-sectional Snapshot | ✅ Native | ❌ No | ❌ No | ❌ No | ❌ No | ❌ No |
| Setup Complexity | 🟢 Low | 🔴 High | 🟡 Medium | 🟢 Low | 🟢 Low | 🟢 Low |
| IC Analysis | ✅ Native | ✅ Yes | ❌ No | ✅Yes | ❌ No | ❌ No |
| Long / Short / Long-Short Rebalancing Quantile Backtest | ✅ Native | ✅ Yes | ⚠️ Indirect | ❌ No | ❌ No | ❌ No |
| Factor Return Attribution | ✅ Native | ⚠️ Indirect | ❌ No | ❌ No | ❌ No | ❌ No |
| Multi-Frequency Support | ✅ Any (microsecond → yearly) | ⚠️ Limited | ⚠️ Mostly daily | ⚠️ Mostly daily | ⚠️ Limited | ⚠️ Limited |
| Coupling | 🟢 Low | 🔴 High | 🟡 Medium | 🟢 Low | 🟢 Low | 🟢 Low |
While AlphaPurify may look similar to Alphalens, it goes far beyond IC analysis and simple graphs.
It supports long, short, and long-short rebalancing backtests, factor cleaning, atributions and delivers a new generation of interactive visualizations by Plotly.
AlphaPurify is different from libraries like QuantStats and Pyfolio, which primarily focus on analyzing return curves and portfolio performance, not backtests. Compared to tools like Qlib and Backtrader, AlphaPurify directly provides a lightweight, fast factor-driven rebalancing backtesting framework and more useful functions — eliminating the need for users to build custom pipelines or infrastructure in these libraries.
In short, AlphaPurify provide quants with a whole factor testing pipeline and beautiful interactive reports to rapidly validate ideas.
Quick Start
1.Install with pip
Users can easily install AlphaPurify by pip according to the following command.
pip install alphapurifyNote: pip will install the latest stable AlphaPurify. However, the main branch of AlphaPurify is in active development. If you want to test the latest scripts or functions in the main branch. Please install AlphaPurify with clone.
2.Load your DataFrame
| datetime | symbol | close | volume | alpha_003 | momentum_12_1 | vol_60 | beta_252 |
|---|---|---|---|---|---|---|---|
| 2024-01-01 09:30 | AAPL | 189.9 | 120034 | 0.42 | 0.15 | 0.21 | 1.08 |
| 2024-01-01 09:31 | AAPL | 190.0 | 98321 | 0.38 | 0.16 | 0.22 | 1.07 |
| 2024-01-01 09:32 | AAPL | 190.4 | 101245 | 0.41 | 0.17 | 0.23 | 1.06 |
| 2024-01-01 09:30 | MSFT | 378.5 | 84211 | -0.15 | -0.05 | 0.18 | 0.95 |
| 2024-01-01 09:31 | MSFT | 378.9 | 90122 | -0.12 | -0.04 | 0.19 | 0.96 |
| 2024-01-01 09:32 | MSFT | 379.1 | 95433 | -0.08 | -0.03 | 0.20 | 0.97 |
P.S. Your DataFrame must include a time column, an asset identifier column, a price column, and your factor column to ensure proper usage.
3.Creating backtesting reports
from alphapurify import AlphaPurifier, FactorAnalyzer, PureExposures

# preprocess
df = (
    AlphaPurifier(df, factor_col="alpha_003")
    .winsorize(method="mad")
    .standardize(method="zscore")
    .to_result()
)

#backtest
FA = FactorAnalyzer(base_df=df,
                    trade_date_col='datetime',
                    symbol_col='symbol',
                    price_col='close',
                    factor_name='alpha_003')
FA.run()
FA.create_long_return_sheet()
FA.create_long_short_return_sheet()
FA.create_short_return_sheet()
FA.create_single_fac_ic_sheet()

#contributions of other factors
Ex = PureExposures(
    base_df=df,
    trade_date_col='datetime',
    symbol_col='symbol',
    price_col='close',
    factor_name='alpha_003',
    exposure_cols=['momentum_12_1', 'vol_60', 'beta_252'],
)

Ex.run()
Ex.plot_pure_exposures()
Ex.plot_pure_returns()
Ex.plot_pure_exposures_and_returns()
Ex.plot_correlations()
Examples of Backtesting Reports
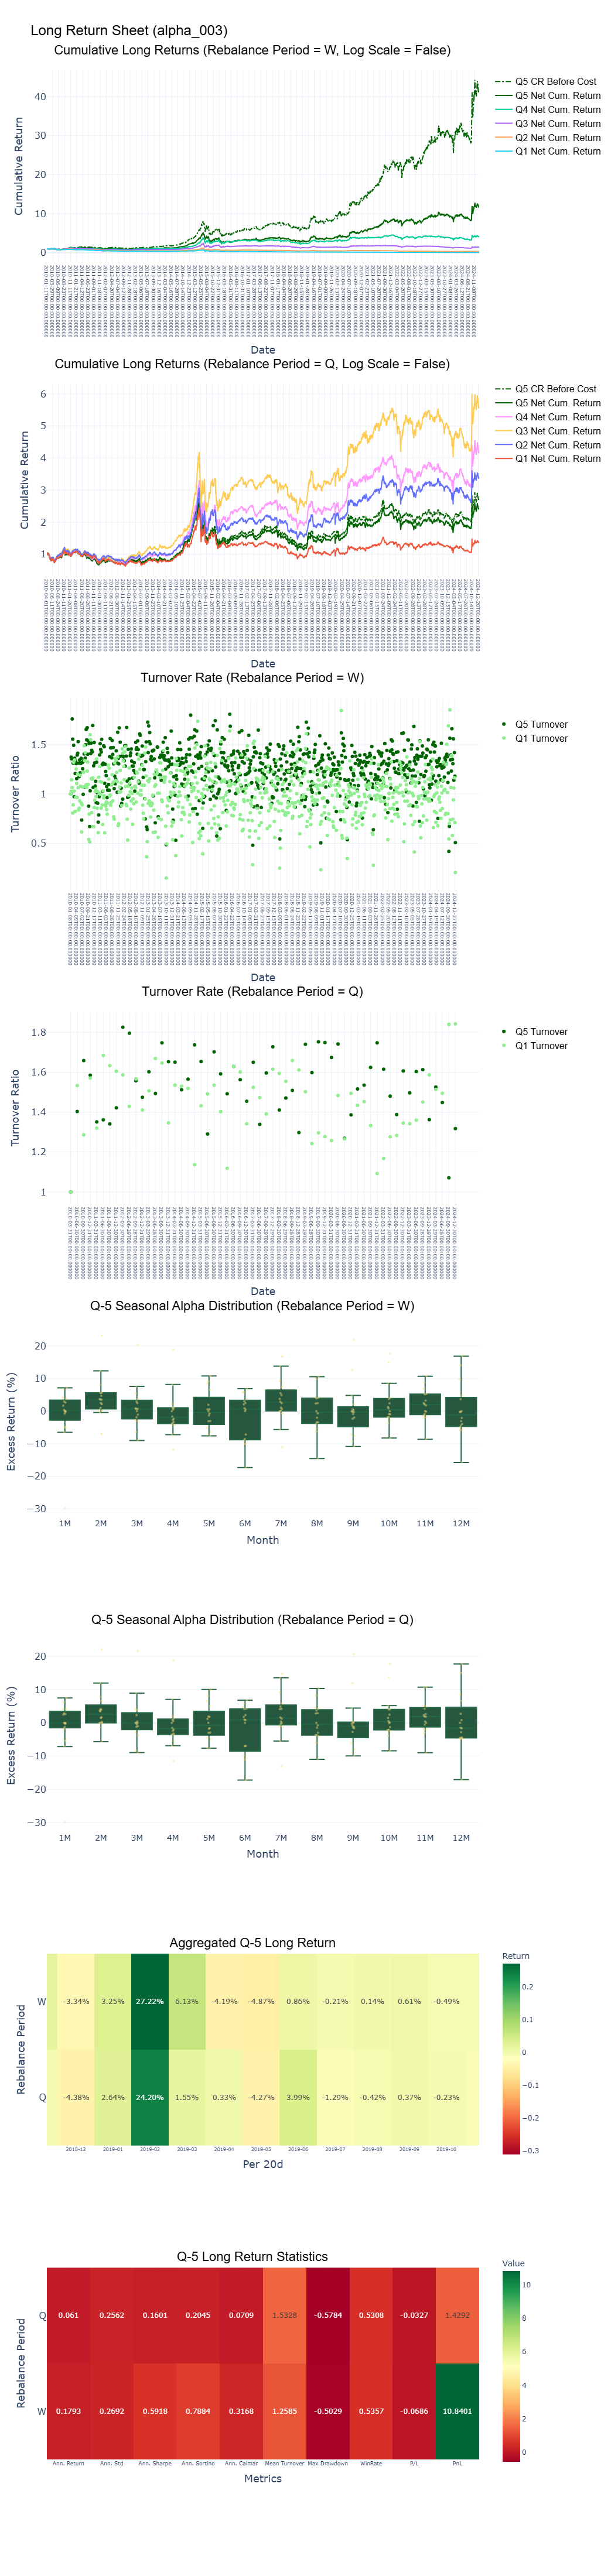
Portfolio for long positions only:
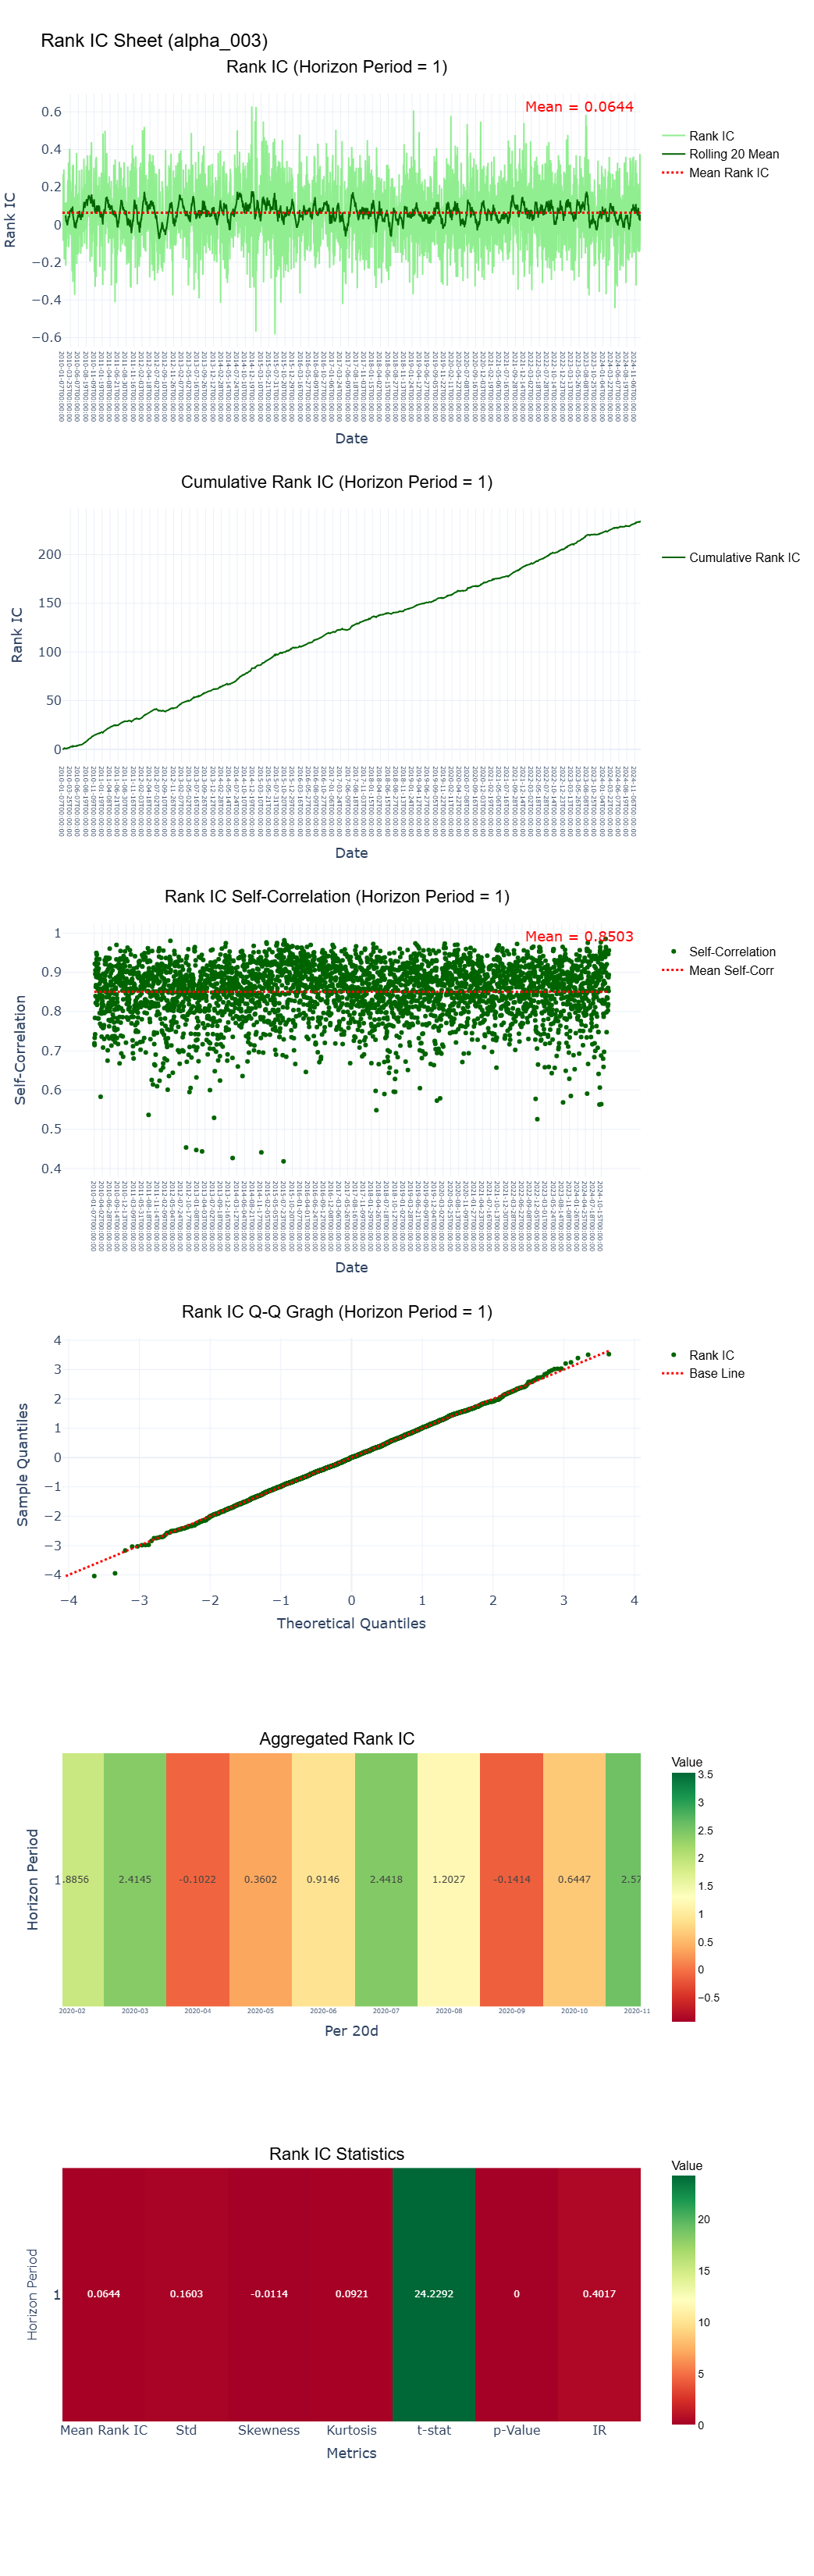
IC Analysis:
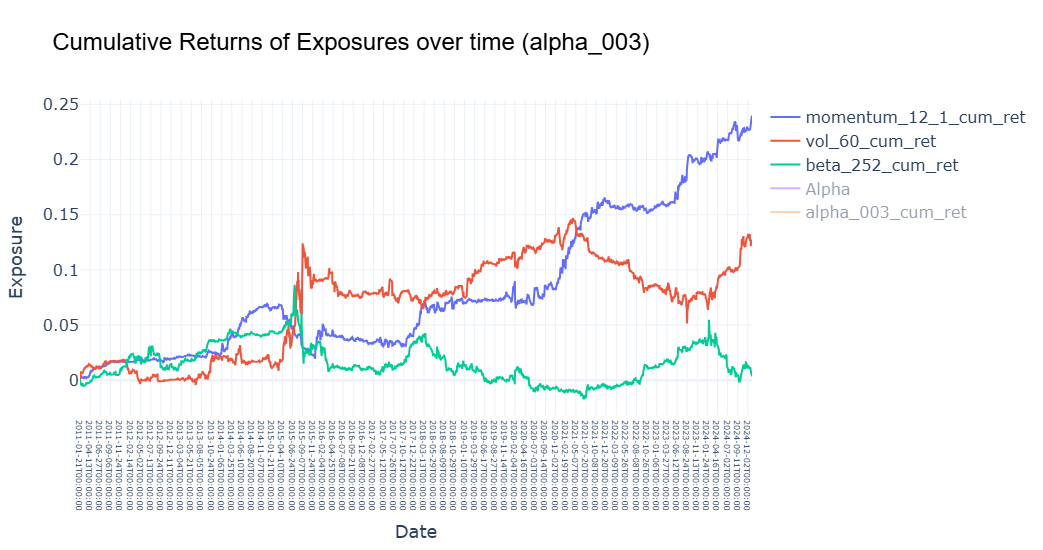
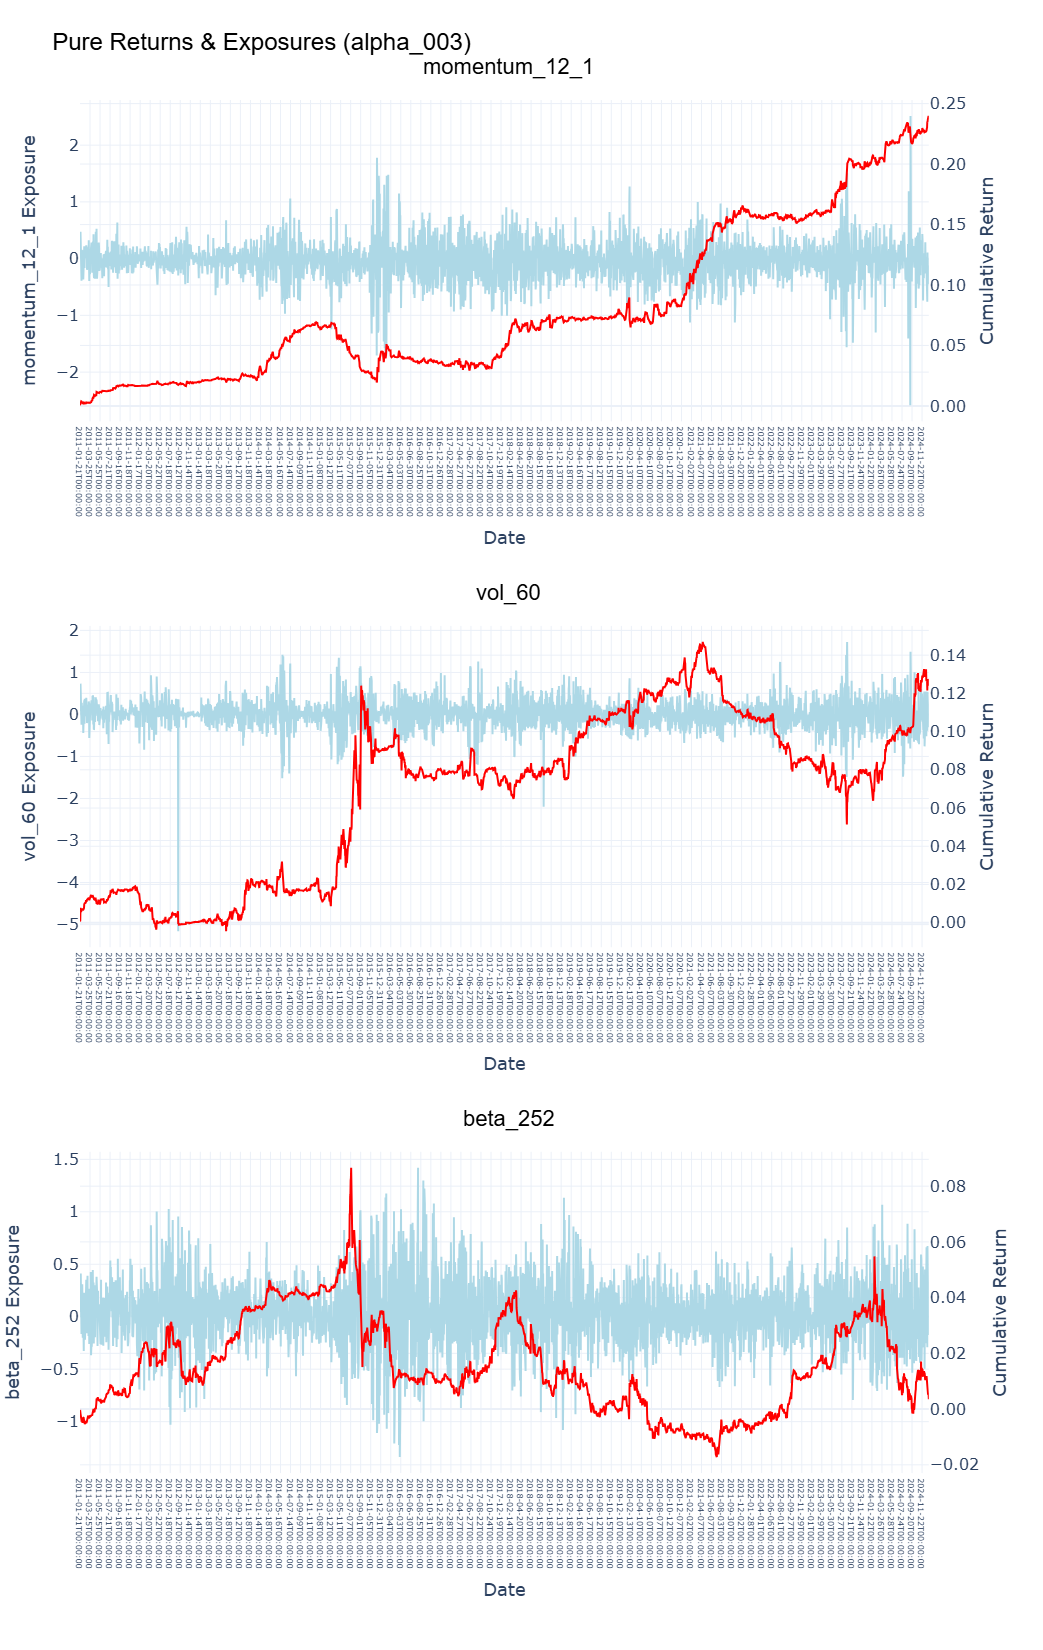
Return attributions of other factors:
What's NEW!💖 — FactorAnalyzer.trace( )
4.Cross-sectional Snapshot: Empowering you to visually track weight transitions and asset returns at ANY timestamp, for ANY position direction, and within ANY quantile bin!
#For example, if you want to see the situation of the first bin for quarterly rebalancing of long positions on 2012-09-28

FA.trace("Q",'2012-09-28 00:00:00',position="l",bins=[1])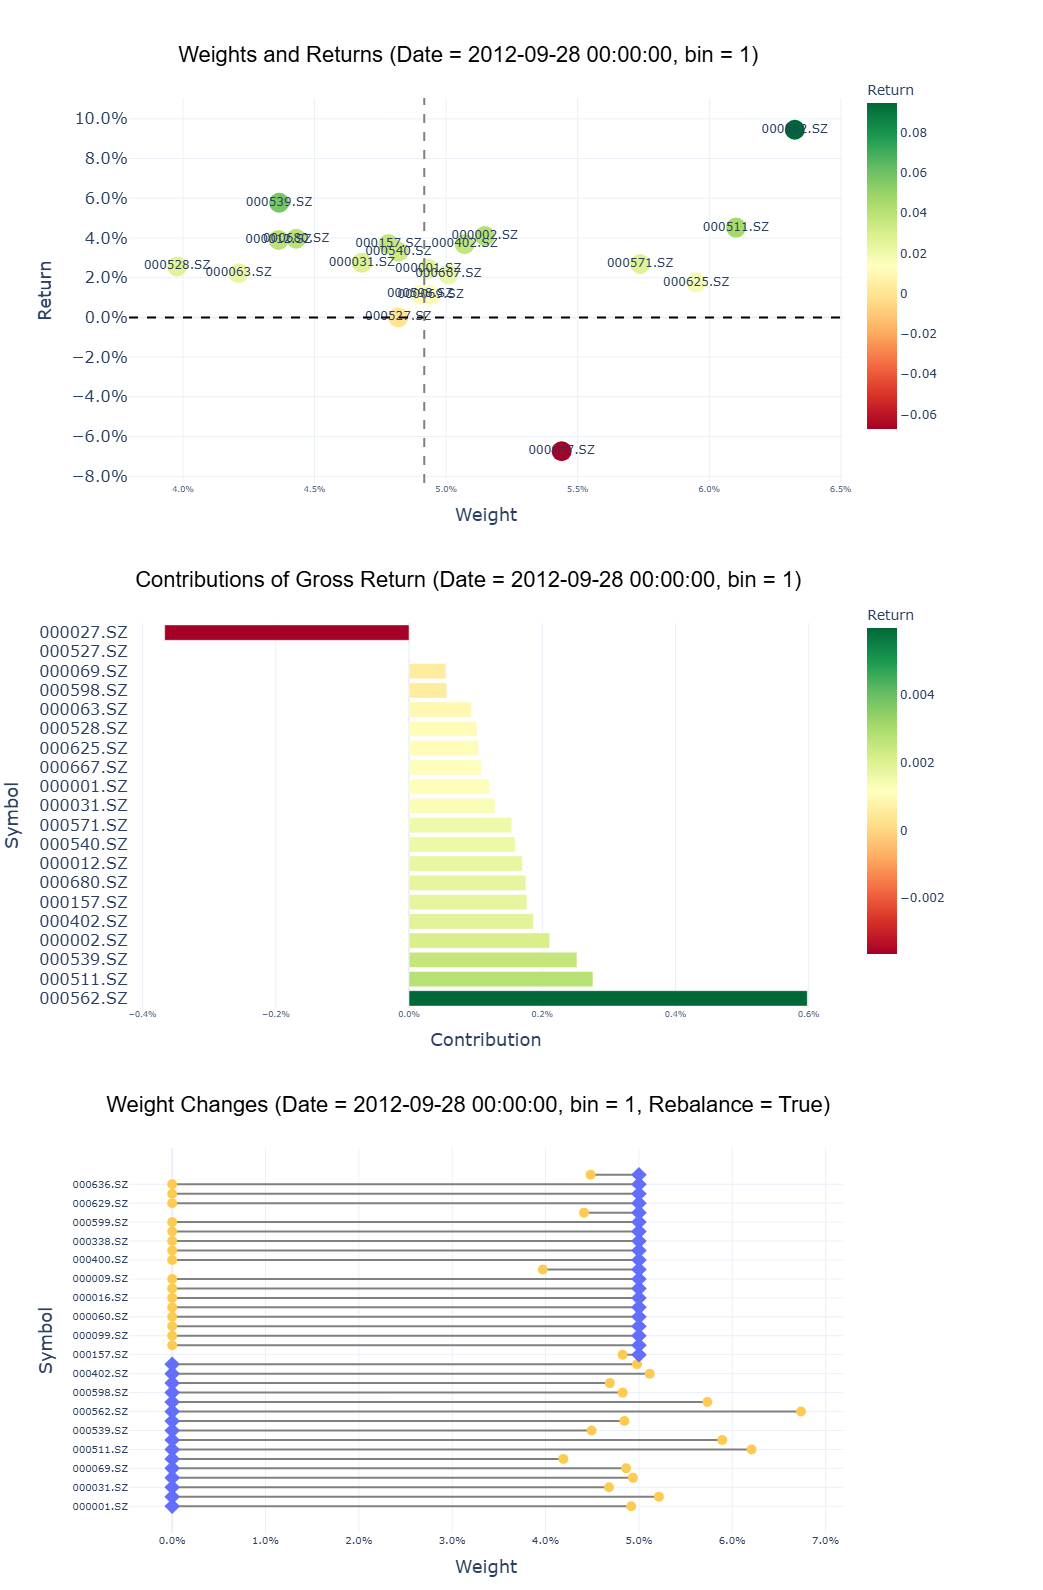
Questions or Feedback?
If you have any questions, run into bugs, or want to suggest new features, feel free to open an issue or start a discussion. I'd love to hear from you!
If you like AlphaPurify, please star & fork this project to support the development!
Elias Wu